News & Insights
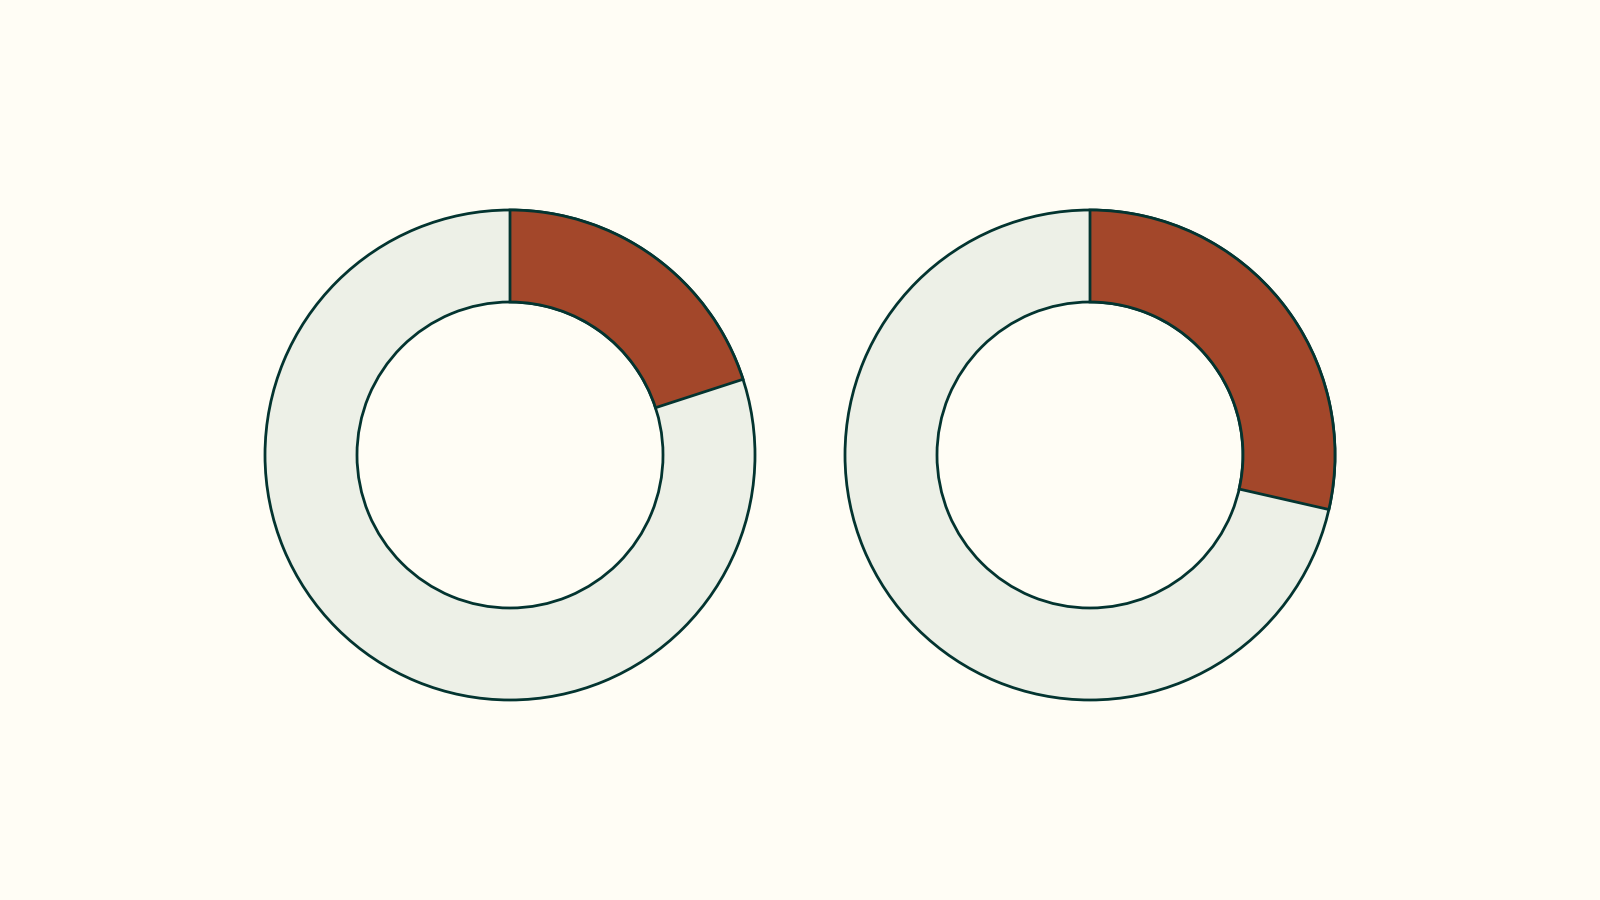
Same equity risk, twice the franking
A retirement portfolio is about half growth and half defensive. Inside the growth half, Australian shares pay a credit that comes back as cash to a pension-phase retiree, and foreign shares pay a tax that does not. Holding that slice through a hedged equity fund collects franking on 29% of the portfolio while putting 20% at risk.
A capital allocation masterclass

David Jones went into administration last Thursday. Twelve years ago its board had three options and took $4.00 a share in cash. What each of the three turned out to be worth, and what the chief financial officer who helped get it done did next at Metcash.

CSL: how a long-term position gets sold

We had never owned CSL. We bought our first shares in January 2026, built the position to nearly 6% of the fund by late August, and started selling two days after the result. The companion to Judo Bank, told from the other end: what a long-term horizon is a willingness to do, and what happens when the price does the re-judging.
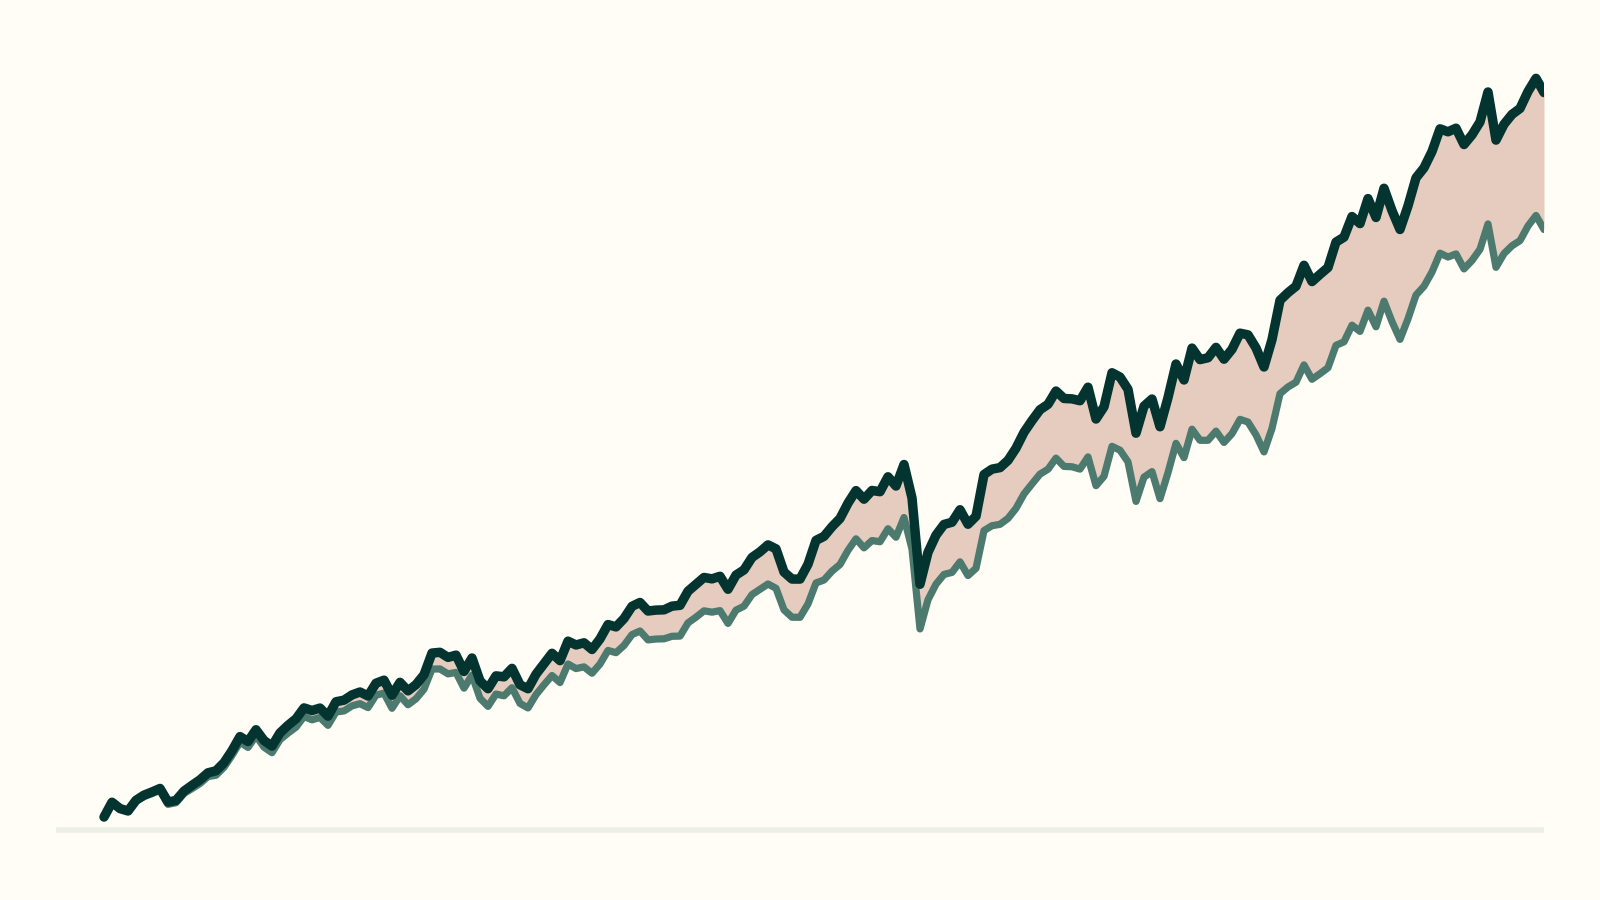
The 1.4% a year your performance table doesn't show
Over fifteen years the Australian sharemarket returned 9.75% a year. It also returned 11.14%. The difference is franking — bigger than most fees, and missing from most performance tables. Where it comes from inside a portfolio, why a 70/30 blend collects only about seven-tenths of it, and why it belongs on both sides of any comparison.
Postcard from Malaysia: at the front lines of the AI infrastructure build
The largest Australian float in thirty years was pulled on 9 October. We had been in Malaysia days before, meeting the people who build and operate this capacity. What we found was a real cost advantage that belongs more to the place than to the company, and a wave of supply arriving over the next two years.

Why we no longer own a major bank
In August 2025 we put a paper to our advisory board setting out what we thought of Australia's major banks. We owned two of them then and none of them now. Here is the argument, what a visiting investor said about why large funds cannot act on it, and where the numbers sit today.
Twenty companies, two-thirds of the index
Twenty companies are 64% of the ASX 200 — and only three of them trade below their own five-year median multiple, against 99 of the 162 outside the top twenty. The gap survives every cut we tried.
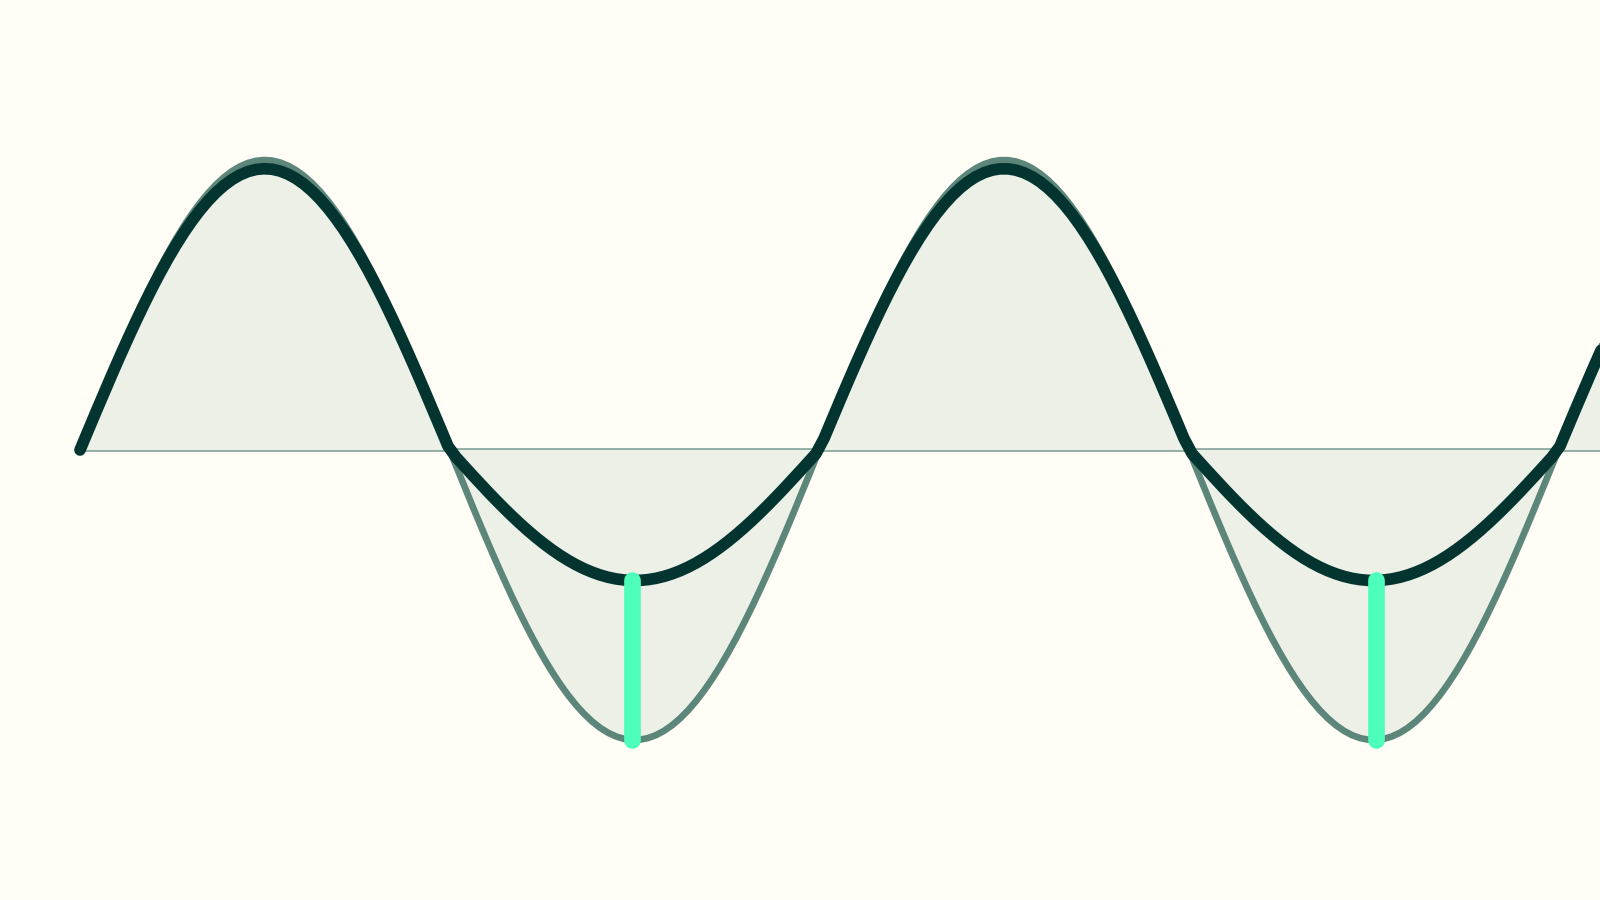
Upside and downside capture: read them together
A low downside capture number can be bought with cash, and it costs upside in the same motion. Why the spread between the two is the figure that matters, and how to check a fund.
Aurizon: what we asked the board for, and what happened
We wrote to Aurizon's directors three days after a $2.35bn acquisition, and kept writing for four years. The chairman answered, then disputed our account of him — and our own Advisory Board talked us out of the third letter.
Judo Bank: how a position gets built
How a 40% one-day fall in a bank we had looked at for a year became a position in our portfolio: the research, the pause at half weight for our Advisory Board, and why liquidity rather than conviction set the final size.
“Success is a culture of integrity, passion and purpose. Deep client trust. Investment outcomes
worth the trust. A business built to outlast us.”
